

This is my second piece on Sea Limited’s strategy in 2026. For the first piece, which is all about Shopee, click here!
Preface
Just like Shopee, Monee also had a wonderful year. The credit business had just passed its critical inflection point and now is in a stage of enormous growth. And I believe the rapid growth phase had just started.
My thoughts on fintech in developing countries are that it’s basically the low-hanging fruit of any successful eCommerce business. It’s a business that could hugely boost the conversion rate of eCommerce transactions and could also help the eCommerce platform enjoy the lucrative profits of a banking institution.
Monee was born out of this backdrop. It serves three goals, which also map to the three stages of Monee’s evolution: 1) increase the conversion rate of Shopee 2) become the default choice of consumer credit 3) become the default app for digital life.
Basically, we are in the second stage of Monee’s transformation, which is increasingly focusing on credit. It doesn’t mean the first goal, increasing Shopee’s conversion, is no longer important. It only means that Monee is starting purse a broader vision, rather than simply acting as a complementary service to Shopee.
Increase the conversion rate
Monee is born to eliminate cash on delivery and to decrease the transaction cost in payment services. Now, with ShopeePay and national payment rails across the region, cash on delivery is no longer very popular in most Southeast Asian countries.
Monee’s goal has shifted from being a payment processor to being a broader payment solutions provider. Monee now provides not only basic payments, but also credit, installment, and monthly subscription services to users.
These services all boost Shopee conversions. One of the recent example is the VIP program in Indonesia. President Chris Feng mentioned this on the recent earnings call:
The renewal rate, it was one of the core challenges historically for a similar program in our region is that payment success rate. When when they roll from one month to another, many people drop off simply because there’s no credit card available for many of our users in our region versus if you look at the more credit card market.
I think we solved this by working closely between Shopee and Monee to enable the smooth payment process for our VIP program. And as a result, our kind of the subscription, re-subscription rate has grown from 40% to 70% in Indonesia over the past few quarters
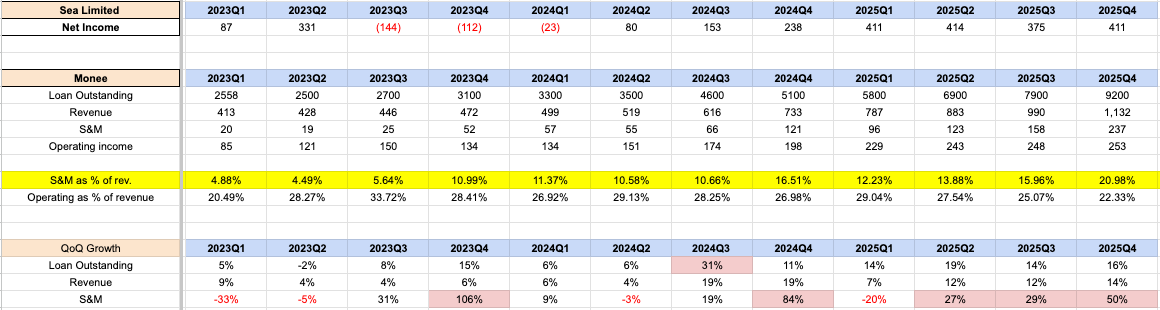
I think Monee’s promotion to improve the conversion rate of Shopee VIP membership is one of several reasons why Monee’s sales and marketing expense has increased sharply in recent quarters. (I’ll talk more about the sales and marketing expense in a moment.)
Become The Default Choice Of Consumer Credit
After Shopee built up its payment business, it began layering in its credit business. In my opinion, in the long term, Shopee’s credit business will be worth a lot more than its eCommerce operation!
The four loan products
There are four main credit products in Monee’s loan portfolio, and they can be divided into two buckets: on-Shopee and off-Shopee.
On-Shopee loans: Working Capital loans (SME loans) and On-Shopee SPayLater (BNPL service that are use on Shopee)
Off-Shopee loans: Cash loans and Off-Shopee SPayLater (BNPL service that are use outside Shopee)
Although working capital loans were the first products launched, consumer loans now account for more than 95% of total loans. And since the end of 2024, more than half of the loans in Asia have been off-Shopee loans. Currently, off-Shopee loans are growing considerably faster than on-Shopee loans.
How Does Monee Scale Up Its Loan Book?
Given the enormous growth in both the loan book and sales expenses, many investors may assume that management is scaling the loan book recklessly.
In reality, the opposite is true. This rapid growth is not a sign of reckless expansion, but rather a result of different product cycles and launch timings across countries overlapping during their scaling stages.
Monee’s first consumer credit product, on-Shopee SPayLater, was launched in Indonesia in 2019, than in Thailand in 2021 and Brazil in 2022. A similar pattern applies to cash loans, which are generally launched 1–2 years after SPayLater. Meanwhile, over the past 18 months, the off-Shopee SPayLater distribution network has only recently begun to come online and scale.
I know this may sound a bit cumbersome, but I will break it down in detail in the following article. For now, let’s return to the question of how Monee scales up its loan book.
Management is scaling up the loan book by fully leveraging Shopee’s ecosystem advantage. As management explained on the 24Q4 earnings call:
In all our markets, on Shopee SPayLater purchases are the first and very natural touch point we have with most of our credit users. It allows them to build an initial credit track record and allows us to build out our credit model for the market.
Once we understand the users’ credit behavior, we give them access to other products with longer tenures and larger quantums. And when we have built a credit risk model for each market that we feel confident of, we then start to scale our loan book. Scaling our loan book includes diversifying into more off-Shopee scenarios, giving us access to a much larger pool of consumer spend.
In essence, management is using a land-and-expand strategy to grow the loan book:
Select a group of users based on shopping behavior.
Give them a low credit limit for SPayLater.
Scale up their SPayLater credit limits.
Give users the option to take out an off-Shopee cash loan.
Scale up their cash loan limits with longer tenures.
This land-and-expand approach is reflected in the disbursement of funds. Despite growing the loan book by 72% year-over-year and 14% quarter-over-quarter, loan disbursements to new users still accounted for less than 10% of total disbursements in the third quarter of 2025. And even more importantly, the loans that Shopee gives out are mostly small-dollar loans with tenures of 1~6 months. The default risk from the macro environment can be adjusted rather swiftly.
The inflection point in Monee’s credit business
There are three things that contributed to the inflection point in 2H24. 1) Shopee has stopped cash burn 2) the credit model is ready 3)the convergence of the product cycle
Shopee has stop cash burn
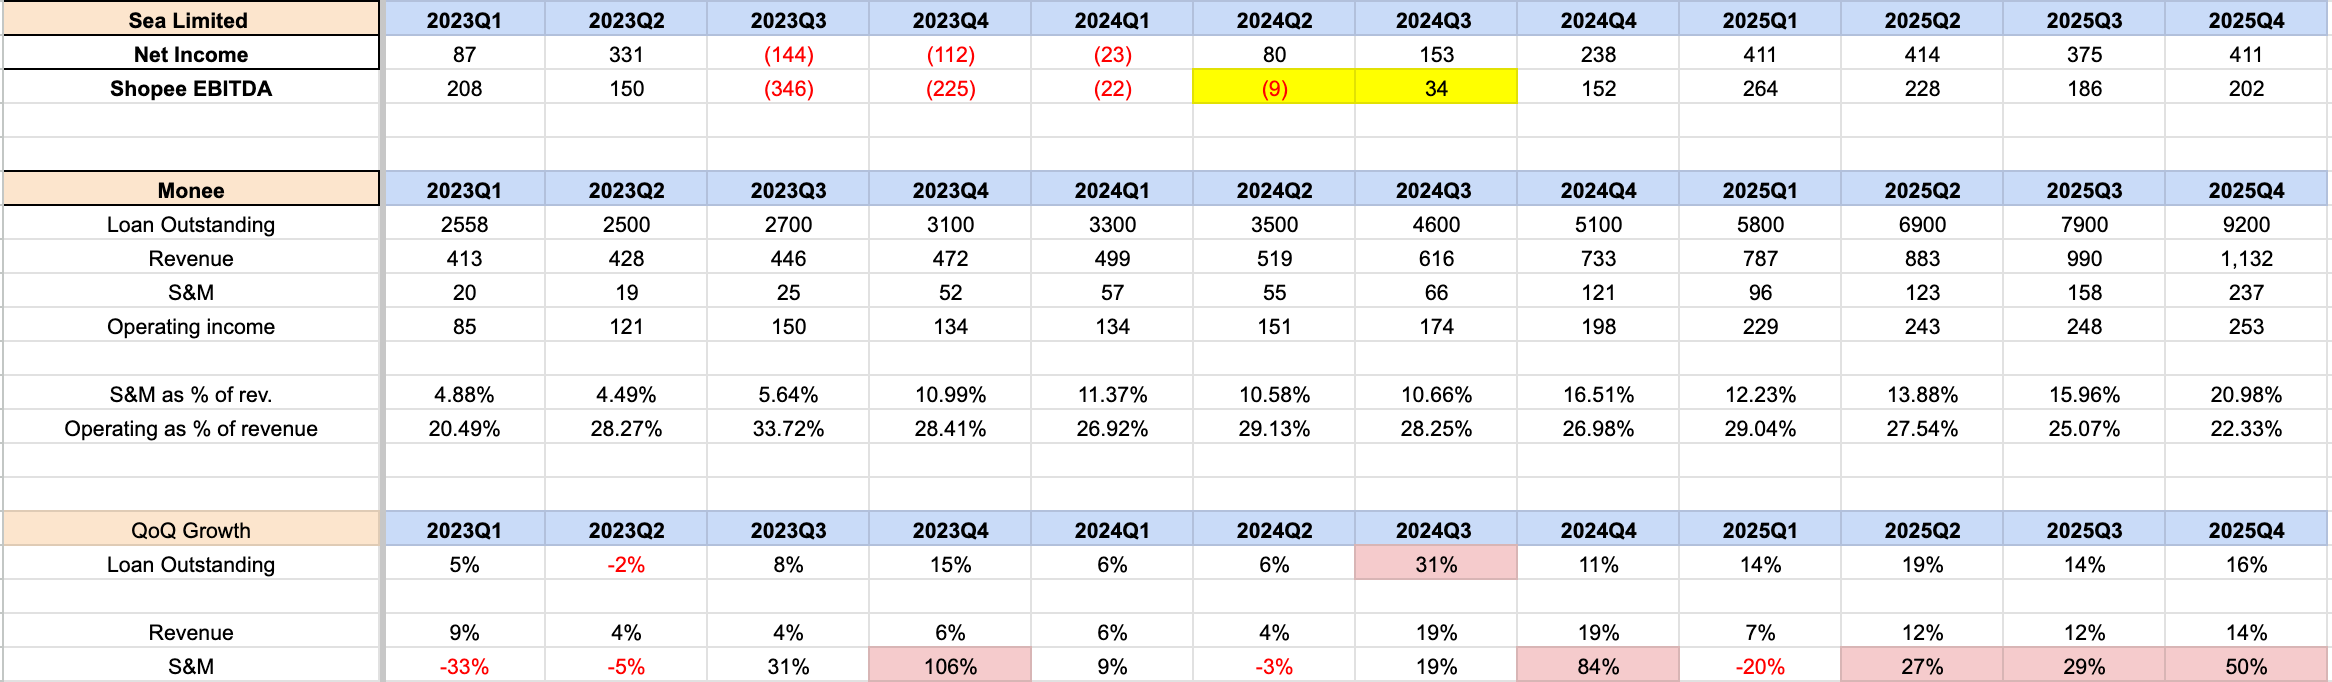
This is the most important reason of all: no matter what, Shopee is the group’s most important asset. Monee still relies heavily on Shopee for distribution. As soon as Shopee stops bleeding cash, Monee has the flexibility to deploy the cash on its balance sheet.
The Credit Model are Finally Ready
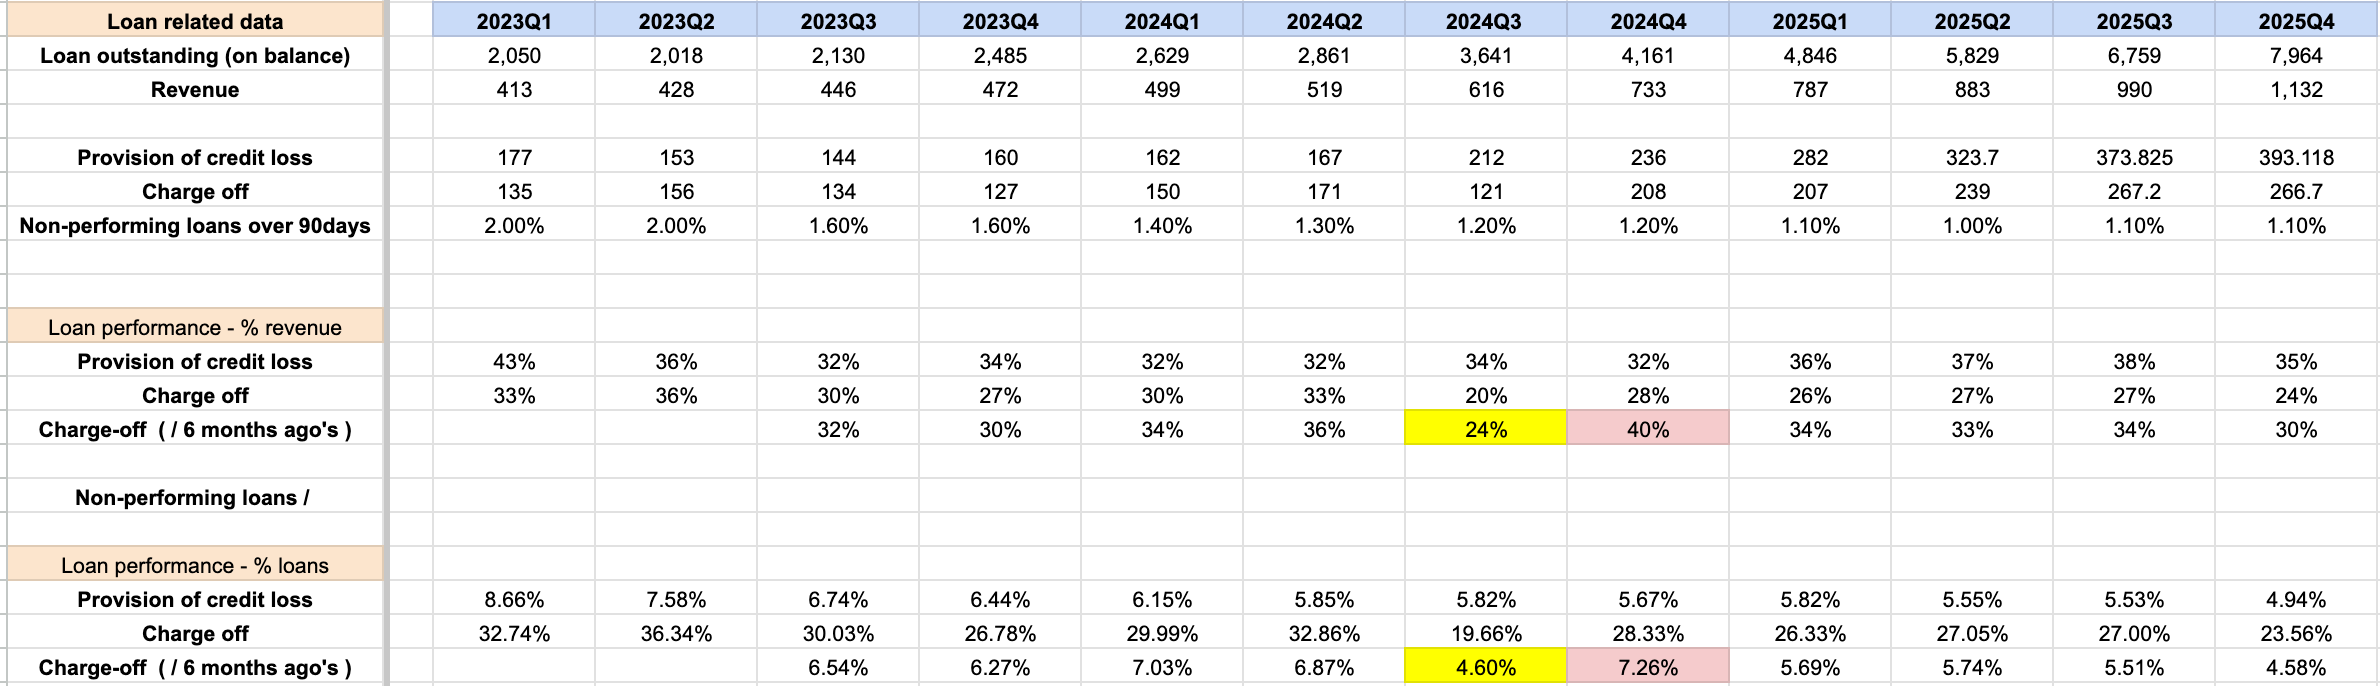
After years of testing, the credit model is ready for mass-market scaling. Non-performing loans over 90 days have declined from 2% to 1.1% in recent quarters.
Since the charge-off has a 4~6 month lag in the loan book, If we compare charge-offs against the loan-book figures from six months earlier, the numbers also appear broadly stable, if not slightly improving.
With better credit models to separate risk, the addressable market can expand into more riskier borrower segments while also allowing Monee to compete more effectively with prime-focused lenders for attractive prime borrowers.
Management has attributed the success in 2025 to AI-driven improvements in the credit model. From the 25Q4 Earnings Call, CEO Forrest Li:
Our credit business expansion in 2025 was made possible by improvements in our risk underwriting capabilities. These improvements tapped on our rich ecosystem data and advancements in AI.
Enhancing our models’ precision and performance enabled us to scale rapidly in 2025 while still maintaining a stable risk profile. Our 90-day NPL ratio held steady at 1.1% as of the end of the fourth quarter.
The Convergence of Product Cycle
In my opinion, Shopee stopping the cash burn frees up the cash to fund loans, while the fine-tuning of credit models makes the products ready for mainstream. And most importantly, the enormous growth is basically attributed to the convergence of product cycles in different countries.
The rollout timelines for the three main consumer lending products are shown below, with Indonesia generally launching first and Brazil latest:
On-Shopee SPayLater: launched in 2019~2022
Cash Loans: launched in 2020~2023
Off-Shopee SPayLater: launched in 2022, but the critical distribution route was launched in 2024Q3 and remains in rollout
1. On-Shopee SPayLater (launched in 2019~2022)
On-Shopee SPayLater is the most mature credit product, and it’s the one with the slowest growth rate. Despite that, we can still expect it to grow much faster than Shopee’s GMV growth over the next few years.
On-Shopee SPayLater is basically the low-hanging fruit. Even till now, a huge percentage of Southeast Asians are still underbanked, so for many users, SPayLater is their first formal credit product. In Indonesia, the credit card penetration rate is merely 7% of the population. Penetration is higher in Thailand and Malaysia, but still well below levels seen in middle and high-income markets such as Taiwan and the United States.
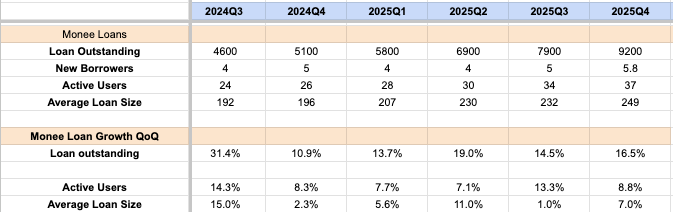
User penetration is also still in the early days. By the end of 2025, Monee had only 37M active credit users, implying that SPayLater had yet to reach even double-digit penetration across Shopee’s 400M+ active buyers.
On the GMV side, penetration also remains modest. In Q2 2025, On-Shopee SPayLater GMV penetration was in the mid-teens on a blended market basis. Meanwhile, at the end of 2024, roughly half of the $5.1B loan book consisted of On-Shopee loans.
The Different Cycles of On-Shopee SPayLater
Since PayLater was launched at very different times across markets, penetration rates also vary meaningfully by country. In Q3 2025, SPayLater GMV penetration ranged from single digits to over 30% in more mature ones.
Excluding Taiwan and Singapore, where underbanking is less of a structural driver, Brazil should be the earliest-stage market. In Q3 2025, penetration there was still in the single-digit to low-double-digit range. Brazil was a decent contributor to Monee’s loan book expansion in 2025, and its on-Shopee SPayLater business still appears to be in a phase of very rapid growth.
Over the long term, I expect on-Shopee SPayLater GMV penetration to exceed 50% across all markets except Singapore and Taiwan. That would imply roughly 200% additional upside in GMV penetration for on-Shopee SPayLater. As a result, I think it’s reasonable to expect on-Shopee SPayLater to continue to grow faster than Shopee’s GMV in the coming years.
2. Cash Loans: launched in 2020~2023
Cash loans reflect Monee’s ambition to take a bigger slice of day-to-day credit. They are currently the dominant form of off-Shopee loans. By the end of 2025, cash loans accounted for roughly half of total loans outstanding. Growth is also materially faster than that of on-Shopee SPayLater: cash loans outstanding almost doubled year-on-year as of Q2 2025.
Monee’s cash loans can be seen as an extension of SPayLater, aimed at capturing more day-to-day borrowing demand outside the Shopee ecosystem. The nature of cash loans makes the average loan balance considerably larger than for SPayLater. Even so, Monee’s current loan portfolio is still largely made up of short-term products designed to meet immediate cash needs.
Compared with traditional bank loans, Monee’s cash loans are more like “small dollar loans,” with considerably smaller ticket sizes and very short payback periods, mostly around 3~12 months. The application process is also much easier and faster, with limited human involvement.
Monee is now actively scaling up borrowing limits and extending loan tenures as it moves further into segments centered on prime users.
From the Q3 2025 earnings call:
In Indonesia, we have been offering higher limits and longer tenures to attract more prime users who demonstrate strong repayment behavior. Loan sizes can typically range from a few hundred dollars to over a thousand dollars, allowing us to serve users with larger financial needs. Building on this success, we have similarly expanded access to prime users in Thailand and Malaysia, where user adoption is going up quickly.
Looking further ahead, I expect Monee to enter areas of secured loans like car loans and mortgages, but I guess it will take another few years. There is still a lot more to explore in the unsecured loans sector, especially in the more prime user case.
3. Off-Shopee SPayLater : Launched in 2022~
The business logic behind off-Shopee SPayLater is very different compared to on-Shopee SPayLater and cash loans. Off-Shopee SPayLater is basically a brand new category!
On-Shopee SPayLater and cash loans are both businesses that mostly rely on Shopee distribution. Shopee merchants in most countries are forced to accept SPayLater, so when scaling on-Shopee SPayLater and cash loans, Shopee does not need to worry about merchant acquisition.
Off-Shopee SPayLater, on the other hand, is built as a substitute for credit cards. It’s a product that involves merchants, consumers, and lenders. It’s a product that needs an enormous off-Shopee distribution to succeed. Monee needs to build the network from scratch.
The SPayLater Distribution Problem
Off-Shopee SPayLater was first introduced in Indonesia in 2022, but after years of recruitment, the number of off-Shopee merchants accepting SPayLater remained limited.
But things started to change in 24Q3 when SPayLater was integrated into Malaysia and Indonesia’s national QR code systems, DuitNow QR and QRIS respectively.
With this integration, the merchant onboarding process became a lot simpler; the merchants no longer need a full and direct integration with SPayLater. As a result, the places that could accept SPayLater have grown exponentially since then, and so have the off-Shopee SPayLater transactions.
By the end of 2025, off-Shopee SPayLater loans had grown over 300% year-on-year, accounting for over 15% of Monee’s total SPayLater portfolio. In Malaysia, close to 30% of SPayLater usage was already off-Shopee, up nearly 10 percentage points from just over 20% two quarters earlier.
Now SPayLater has been integrated with the national payment rails in Malaysia, Indonesia, Vietnam, Thailand, and the Philippines. I think we are safe to expect off-Shopee SPayLater to sustain triple-digit growth in the coming years.
Note: Every country’s national payment rails are different, but they generally drastically reduce the friction for merchants to accept credit and improve interoperability across banks and digital wallets.
The 10x growth ceiling of off-Shopee SPayLater
The off-Shopee scenario represents a significantly bigger market than the on-Shopee scenario. In China, more than 95% of Alipay’s transaction volume came from outside Alibaba’s own properties, and in the U.S., more than half of overall card-based transactions were made through credit cards.
Off-Shopee SPayLater is a three-side marketplace, and Monee is now competing to become one of the top consumer credit options. Monee is not only actively onboarding merchants, but also expanding credit use cases to extend its presence in higher-ticket categories and compete with more traditional forms of credit.
From the 24Q3 and 25Q4 earnings calls, respectively:
One recent example of an off-Shopee use case was to facilitate consumer’s large ticket purchases of mobile phones in offline retail stores.
We also expanded the use of SPayLater into higher-ticket offline categories, such as electronics and two-wheelers.
I think the recent ramp up of the offline scenario to build up the network effect of off-Shopee SPayLater is one of the main reasons Monee’s sales and market expense have been exploding.
Going to a broader market
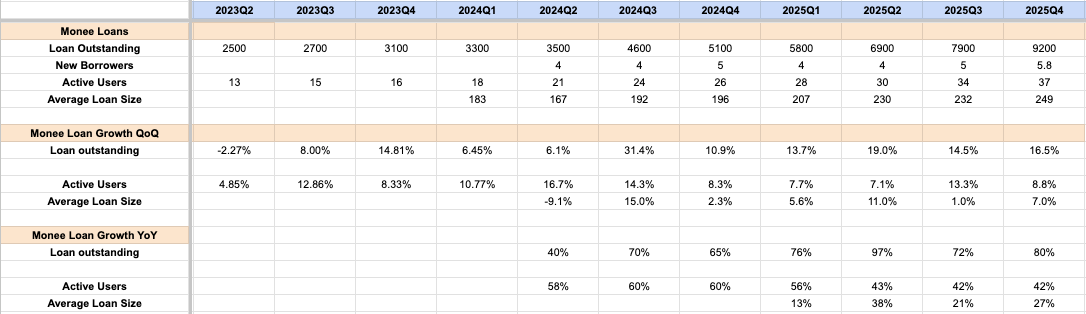
Now Monee has successfully scaled its active credit user base to 37 million. Starting from 25Q3, the management has changed the approach from a “whitelist-based” approach to a broader “all-can-apply” approach and has been progressively rolling it out across markets for both SPayLater and cash loans.
According to management, the strategy has been a success! In 25Q4, Monee landed a record 5.8M new credit users, and the new cohort generally has positive unit economics. I think the shift to the all-can-apply approach is also another of the core reasons S&M spending increased so much.
Based on the 24Q3 earnings call, the management team said they generally target a payback period of less than 12 months. That suggests we should see the results of these initiatives fairly soon.
The Next Stage of Monee: The Default App for Digital Life
Monee’s goal goes far beyond becoming a personal finance super app. The ShopeePay app has a much bigger ambition. It aims to become the default app for digital life, with financial services being just one part of that journey.
(See the screenshot of the Thailand ShopeePay App, translated by Gemini)
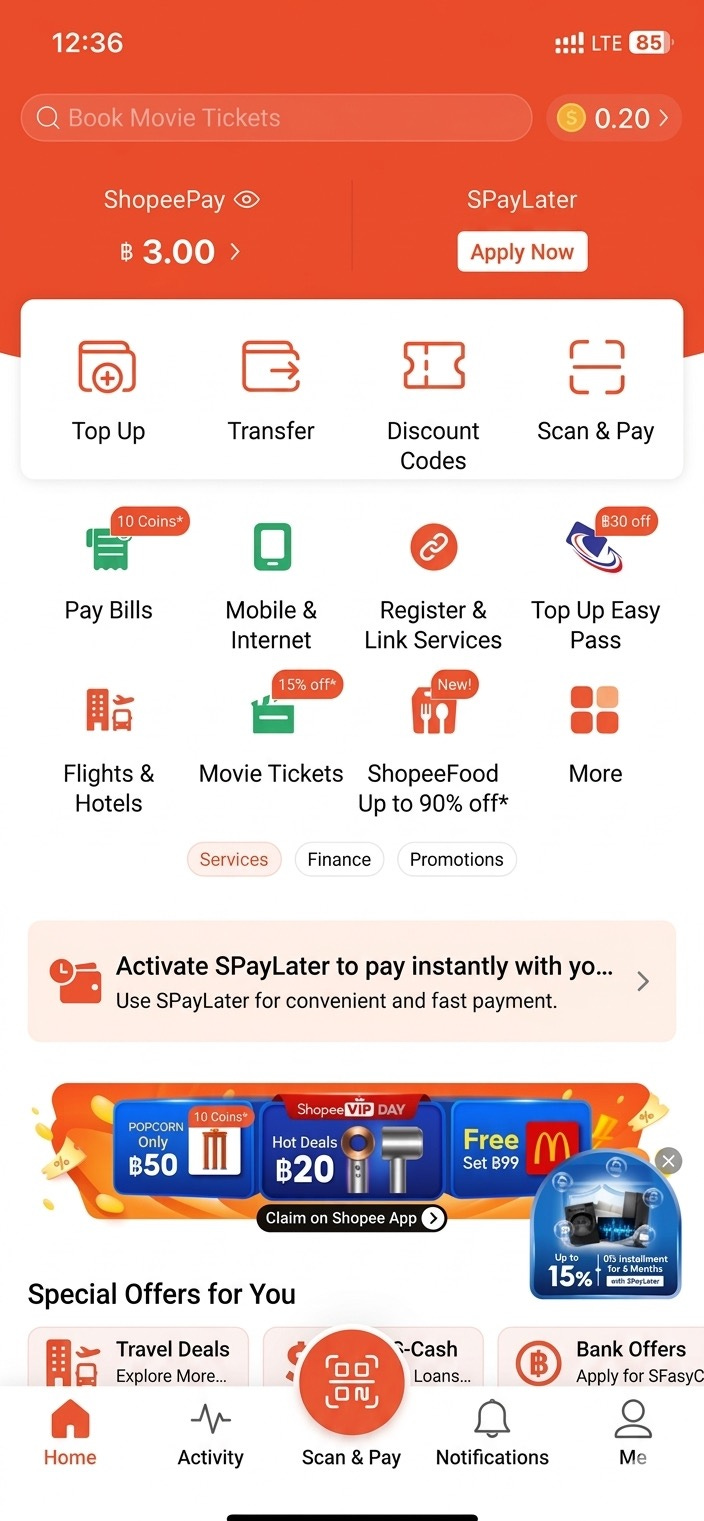
The Indonesia standalone ShopeePay App was launched in February 2024. By March 2025, it had surpassed 30 million downloads, and it has now reached at least 50 million downloads on Android alone. Today, more than 20% of ShopeePay’s monthly transacting users are using the standalone app.
The standalone ShopeePay app is basically an unbundled version of functions from the core Shopee app, and it signals Monee is entering the next stage of its expansion. The standalone app reduces payment friction in non-Shopee scenarios, and simplifies the UI design and frees up space for other lifestyle services.
From the screenshot, we can see users can book tickets, hotels, movies, order food, pay bills, and apply for credit products like SPayLater and cash loans. Everything can be done in one single app! In certain countries, users can also buy insurance, invest in mutual funds, and access other financial products.
For now, however, the services provided by Monee are still rather shallow, and the app’s capabilities remain limited. For instance, just like Grab, its hotel booking function is powered by Agoda. Its other services are also not very competitive compared with other standalone players.
But at this stage, that is not the most important point. Services outside of consumer credit are not Monee’s core focus. The standalone app is currently Monee’s way of improving conversion for its credit products and attracting more credit users from outside the Shopee ecosystem.
Monee is clearly thinking about a much broader picture than just credit. Once the business becomes more mature, it will likely make other services the next area of focus.
Note: The standalone ShopeePay app is currently available in only four countries: Indonesia, Thailand, Malaysia, and Vietnam. In other countries, ShopeePay and related services still remain inside the Shopee app and have not been separated. Interestingly, Indonesia was not the first market to launch the standalone ShopeePay app. There is also one exception: Taiwan is the only Shopee market without ShopeePay.
Another Marketplace
Shopee is a marketplace for physical goods, and Monee is Sea Limited’s ambition to become the marketplace for digital services.
In Southeast Asia, or in most developing countries, supply remains the biggest constraint in a marketplace business. Shopee first solved this supply problem by offering zero commission fees and free shipping to sellers to kick-off the marketplace.
In the beginning, sellers came to Shopee for free shipping to serve their existing customers. With more and more supply, the customers started to stay in the network. Interestingly, the sellers that first used Shopee as a tool for free shipping then got trapped by the consumer traffic and then eventually became sellers on the platform.
It’s similar to building a marketplace for digital services. Take credit services as an example: without existing credit history, traditional banks and credit funders have no idea who is creditworthy. Monee is now the intermediary between the two ends. On one end, Monee leverages its own balance sheet to fund the existing demand. On the other end, Monee trains models to build up financial records to attract future supply.
Now, only about one-tenth of the existing loans are funded by outside lenders. I believe the portion of loans funded by outside funds will grow substantially in the near future, especially when Monee enters more prime-oriented credit. Once that happens, it will become much clearer that Monee is building not just a lending business, but a marketplace for credit.
The Other Marketplaces Yet to Be Built
Among all the other marketplaces that could still be built, digital finance is the most obvious category. Mortgage lending platforms, digital banking platforms, financial advising platforms, insurance-matching platforms, and etc. are all huge opportunities that Monee may try to capture.
There are also a very decent number of O2O services that are essential to day-to-day life but remain highly fragmented in this market or haven’t even been properly developed yet. Monee will probably leverage its distribution to build an aggregation layer across many of these O2O use cases.
I don’t know how well Monee will perform in the future, but Alipay is a strong reference point for the ShopeePay app. It has successfully built marketplaces for many financial services and has also become an aggregation layer for a wide range of services that are relatively commoditized, yet still essential to everyday life.
Closing Thoughts
I think compared to eCommerce, I know a lot less about fintech in general; the whole thing isn’t as easy to write as the Shopee post. Even when I already know what I want to say, checking every detail takes much more time than I expected. But overall, I think I have successfully mapped out the long-term trajectory of Monee’s business and its path toward building another marketplace.
Another thing I want to point out is that I think Monee’s credit risk is a bit overstated. It’s fair to say that Monee has high credit risk, but compared to traditional lending, it is actually already pretty immune to the macro environment. Because its loans have very short tenures and small ticket sizes, management can adjust pricing rather quickly.
And besides, even if all the loans on the balance sheet suddenly default, it also won’t impact Monee’s long-term profitability!
From a macro perspective, the real thing to worry about is that when default rates rise, Monee’s ability to generate revenue will be severely impacted, and it could also undermine years of trust built with future loan funders.
Another thing I haven’t mentioned in the article is that Shopee‘s and Monee’s growth are a bit contradictory. Monee’s current model of funding credit through its own balance sheet is not very sustainable if Shopee does not generate enough profit.
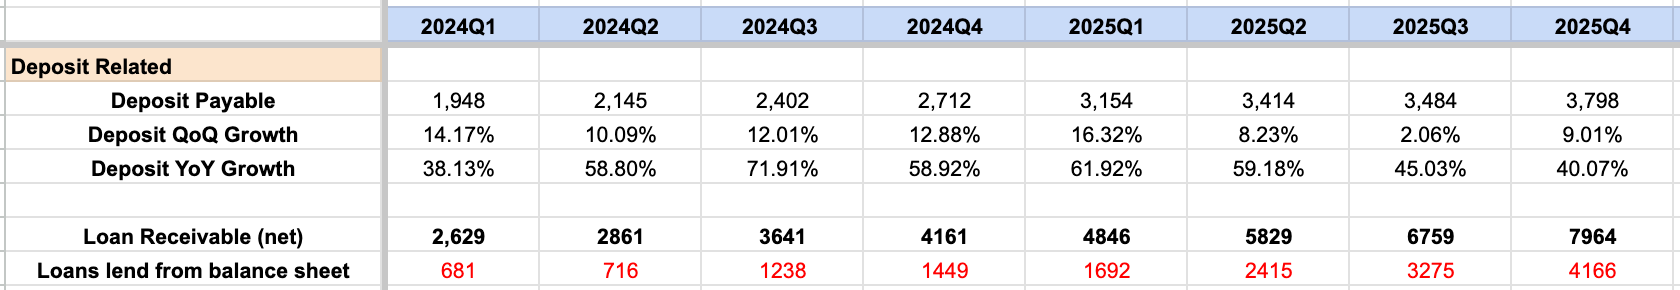
Monee’s digital bank deposits are also not growing fast enough. In the past year, more than $2.7B of loans were funded purely by Sea Limited’s balance sheet. If Sea Limited doesn’t want to shrink its cash balance drastically, it will need to decelerate the speed of loan growth.
Garena
I think compared to fintech, I have even less to say about gaming. I don’t play games, and I know very little about the sector. But despite that, I think Garena also had a wonderful year. Bookings were up 37%, and management is guiding for another double-digit growth year in 2026. At least in the short term, I don’t think gaming will be much of a drag.
My thoughts on gaming are that games are very niche and work in paradigms. The same genre will have a few winners, and the winner will last a very, very long time. If you look at the top games in the world, nearly all of them were first launched more than a decade ago. Good games can become evergreen franchises, and I believe Free Fire is already one of them. Because of that, I’m not too concerned about its long-term sustainability.
In the past few years, the management team seems to have cracked the code for driving growth through deep collaboration with other IPs, such as Squid Game and NARUTO. I believe in the future, the growth trajectory will also highly depend on these IP collaborations. So bookings and revenue would probably fluctuate more accordingly.
Thanks for reading!
Another side note. I’m very grateful to have received quite a number of messages from fund managers and thoughtful individuals offering pushback and valuable insights. If you fall into this category, please feel free to shoot me a DM. I’d love to stay in touch.
If you are worried about taking up too much of my time, or if you simply want some help speeding up your understanding of eCommerce, or want to know more about my investing philosophy, you can now also reach out to request a paid expert call. I have done a few already, and the feedback has been very good.
I’m very grateful to have this opportunity.
Thanks for the article!
I have a few stupid questions about various loan type shares:
1. "By the end of 2025, cash loans accounted for roughly half of total loans outstanding." - does it mean 50% of the whole loan book or 50% of Off-Shopee loan book?
2. "since the end of 2024, more than half of the loans in Asia have been off-Shopee loans". Did SEA disclose this somewhere or is this statistics sourced elsewhere?
Taking a step back, where is Monee in the overall fintech landscape in each country? Can they reliably gain market share from incumbent players - TnG in Malaysia Momo Zalopay in Vietnam and host of wallets in Indonesia Mercado Pago in Brazil. Fintech is super competitive and banks have superior cost of lending - national payment rail almost ensure banks will play a big role in the financial landscape. Quite bullish in $SE but want to offer some perspective given my fintech background in SEA.